What to Do After an Accident in a Leased Car (That Wasn’t Your Fault)
 By Eric Rayz
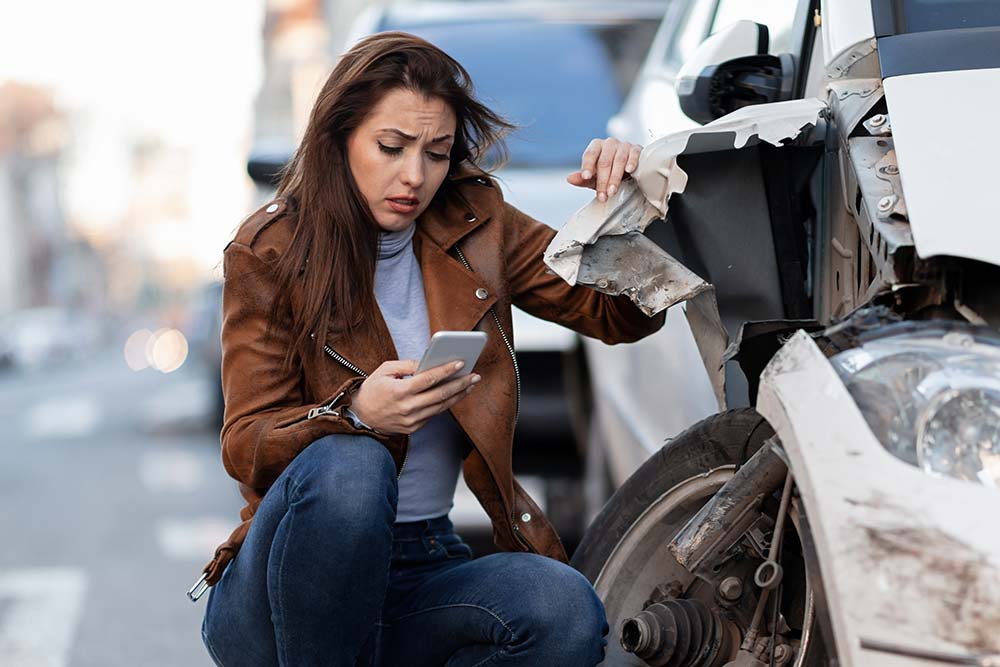
A car accident is stressful under any circumstances, but leasing your vehicle adds a layer of complexity most drivers don’t expect to navigate. Beyond the usual questions about medical bills and repair costs, you’re also dealing with a leasing company that has its own expectations for the car’s condition, along with lease terms that weren’t written with an accident in mind.
If you weren’t at fault, you shouldn’t be the one left covering the gap between what your insurance pays and what you still owe on the lease. Understanding how these pieces fit together early on can make a real difference in how smoothly your claim moves forward. It’s often where a Philadelphia car accident lawyer can help make sense of a situation that isn’t as straightforward as it looks.
What to Do Right Away After a Leased Car Accident
The first steps after an accident are largely the same whether you own or lease your vehicle, but a couple of extra items belong on the list when a leasing company is involved.
- Check for injuries and call the police. Get medical attention if needed and make sure an official accident report gets filed.
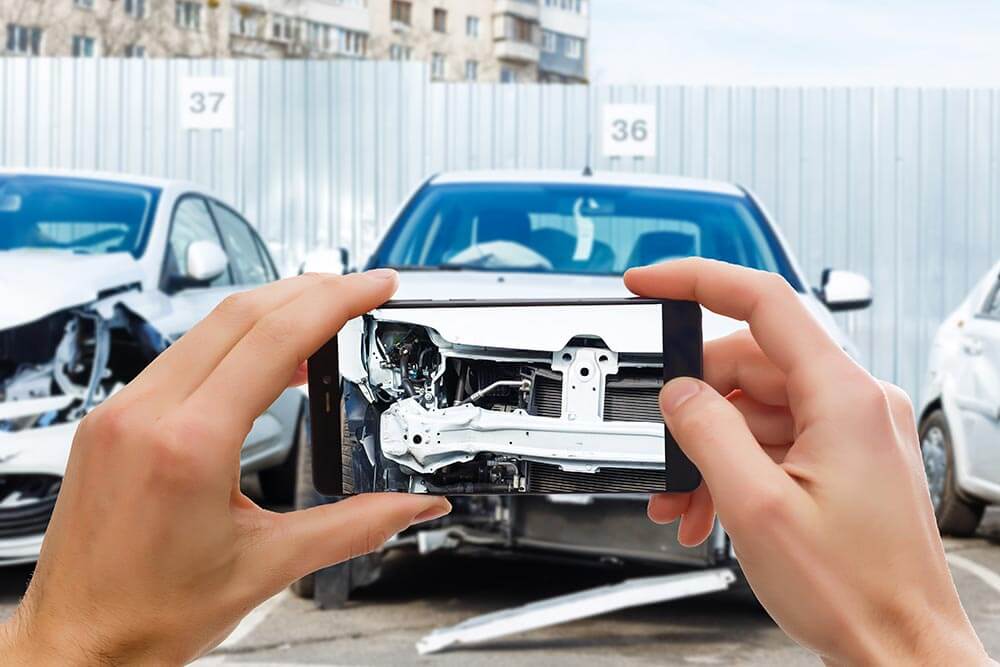
- Document the scene. Photos of the vehicles, the damage, and the surrounding area can matter later, especially if fault is disputed.
- Exchange information with the other driver. Collect names, contact details, and insurance information on the spot, if possible.
- Notify your insurance company. Most auto insurance policies require prompt reporting, even when you weren’t at fault.
- Contact your leasing company. This step is easy to overlook, but leasing companies often want to know about significant damage and may have requirements about where repairs are done.
- Hold off on major repair decisions until you’ve heard back. Committing to a repair shop or a settlement figure before understanding your lease terms can create problems down the line.
If the claims process starts to feel complicated or the insurance company isn’t cooperating, it may be worth considering a Philadelphia car accident lawyer to help sort through your options.
Who’s Responsible for the Damage?
Even when another driver caused the accident, your relationship with the leasing company doesn’t change. You signed an agreement to return the vehicle in good condition, and that obligation doesn’t disappear just because someone else was at fault. This means you’re still responsible for making sure the car gets repaired properly and that the leasing company stays in the loop.
That said, not being at fault still matters a great deal for how the claim itself gets handled. In most cases, the at-fault driver’s insurance is responsible for covering the damage, which means their insurer, not yours, typically pays for repairs or issues a total loss payout. Pennsylvania drivers do carry their own Personal Injury Protection coverage for certain medical costs, but property damage claims like this one generally still fall on the driver who caused the crash.
That’s why documenting the accident thoroughly matters so much. If liability is disputed, or if the at-fault driver’s insurer tries to minimize the payout, clear evidence from the scene can make it easier to hold the right party accountable and avoid absorbing costs that shouldn’t be yours.
When a Leased Car Is Totaled: How the Payout Works
A car is generally considered a total loss when repair costs exceed a certain percentage of its value, at which point the insurance company decides it makes more financial sense to pay you out than to fix the vehicle. That payout is based on the car’s actual cash value, meaning what it was worth right before the accident, not what it would cost to replace it or what you might still owe on the lease.
Why the Payout and the Lease Balance Rarely Match
This is where leased vehicles create a problem that owned vehicles usually don’t. Because lease payments are structured around the vehicle’s expected depreciation, what you owe the leasing company at any given point doesn’t necessarily match the car’s actual cash value. Depending on how far into the lease you are, that gap can be small or substantial.
If the insurance payout is less than your remaining lease balance, you’re generally still responsible for covering the difference under your lease agreement, even if you weren’t at fault.
"If I see things that are unjust or unfair, it's hard to separate myself. It's outrageous to witness the insurance carrier take the position that there was no accident, no injury, or that the person was never at the scene of the accident. And they often take those positions without any evidence whatsoever."
The Role of GAP Insurance
GAP insurance, short for “Guaranteed Asset Protection,” covers the difference between what your auto insurer pays out on a totaled vehicle and what you still owe your leasing company. Without it, that gap becomes your responsibility, regardless of who caused the accident.
Some leases include GAP coverage as part of the agreement, while others leave it up to you to purchase separately. If you’re not sure whether your lease includes it, your leasing agreement or your insurance agent should be able to tell you. It’s worth checking sooner rather than later, since finding out after an accident that you don’t have coverage can turn an already stressful situation into a costly one.
Even with GAP coverage, it’s a good idea to contact your leasing company directly after an accident. Some agreements have specific notice requirements or documentation you’ll need to provide before GAP coverage kicks in.
What If the Insurance Payout Doesn’t Cover What You Owe?
Even with GAP insurance, drivers may still question whether the payout they received was fair. Insurance companies sometimes value a totaled vehicle lower than expected, particularly if they rely on comparable sales data that doesn’t fully reflect the car’s condition, mileage, or added features.
If the initial offer seems low, you can generally push back. This might involve providing your own comparable listings, documentation of recent maintenance or upgrades, or an independent appraisal. Insurers don’t always volunteer this option, but disputing a valuation is a normal part of the claims process, not an unusual request.
In some cases, drivers also raise the issue of diminished value, the idea that a vehicle is worth less after being in an accident even if it’s fully repaired rather than totaled. Whether this applies depends heavily on the specifics of the claim and the insurer involved, but it’s worth understanding if you’re weighing whether an offer reflects the accident’s true impact.
How Long Does This Process Take?
Between the insurance company’s evaluation, the leasing company’s paperwork, and any back-and-forth over the payout amount, resolving a claim involving a leased vehicle can take longer than people expect. Straightforward claims may wrap up in a few months, while disputes over fault or valuation can stretch the timeline considerably.
Keep in mind that insurance and leasing deadlines aren’t the only ones at play. Pennsylvania law generally gives injured individuals two years from the date of an accident to file a personal injury lawsuit, and this deadline exists separately from anything happening with your insurance claim or your lease. Even if you’re still working through repairs, payouts, or lease paperwork, that legal clock is running in the background, which is part of why it’s worth understanding your options sooner rather than later, even if you don’t end up needing to take legal action.
When You’re Ready, Kalikhman & Rayz Is Here to Help
Dealing with a leased car accident that wasn’t your fault brings its own set of headaches, especially once insurance claims and lease terms start pulling in different directions. At Kalikhman & Rayz, we help clients across Pennsylvania work through those pieces. We want the process to feel less overwhelming, so we figure out who’s responsible for what and make sure a low insurance payout doesn’t become a problem you have to solve alone.
If you’ve been in an accident involving a leased vehicle and it wasn’t your fault, reaching out to a car accident lawyer can be a useful next step. Contact our firm for a free consultation and to talk through your options.


You Might Also Like
Pennsylvania Car Insurance Requirements
Nov 12, 2026

Someone Borrowed My Car and Got in an Accident. What Happens Now?
Nov 12, 2026

Can I Lose My House Due To An At-Fault Car Accident in Pennsylvania?
Nov 12, 2026

Can You Claim Your Car Accident Without a Police Report?
Nov 12, 2026
How Much Does Insurance Go Up After a Car Accident in Philadelphia
Nov 10, 2026
12 Things to Do After Being Involved in a Car Accident
Nov 10, 2026
Understanding the Timeline of a Philadelphia Car Accident Claim
Nov 10, 2026
What to Expect After a Car Accident in Philadelphia
Nov 10, 2026
How Much Does a Car Accident Lawyer Cost in Philadelphia
Jul 30, 2026
When Is It Too Late to Get a Lawyer After a Car Accident in Philadelphia?
Oct 2, 2026